What cash sits outside the down payment?
Budget separately for applicable stamp duty, legal and loan documentation charges, valuation, insurance or takaful, furnishing and moving costs. Whether any cost is borne by another party must be established in writing. Keep emergency cash separate; the table is not a complete cash-to-complete quotation.
What happens before the full mortgage starts?
For a home under construction, disbursement and progressive interest can follow a different timeline from the eventual full instalment. Ask the bank for the payment schedule for your loan and allow for any overlap with existing rent. The calculator has a separate payment-timeline tool; do not add its example to the table as though every loan follows the same timing.
How do these budgets relate to projects?
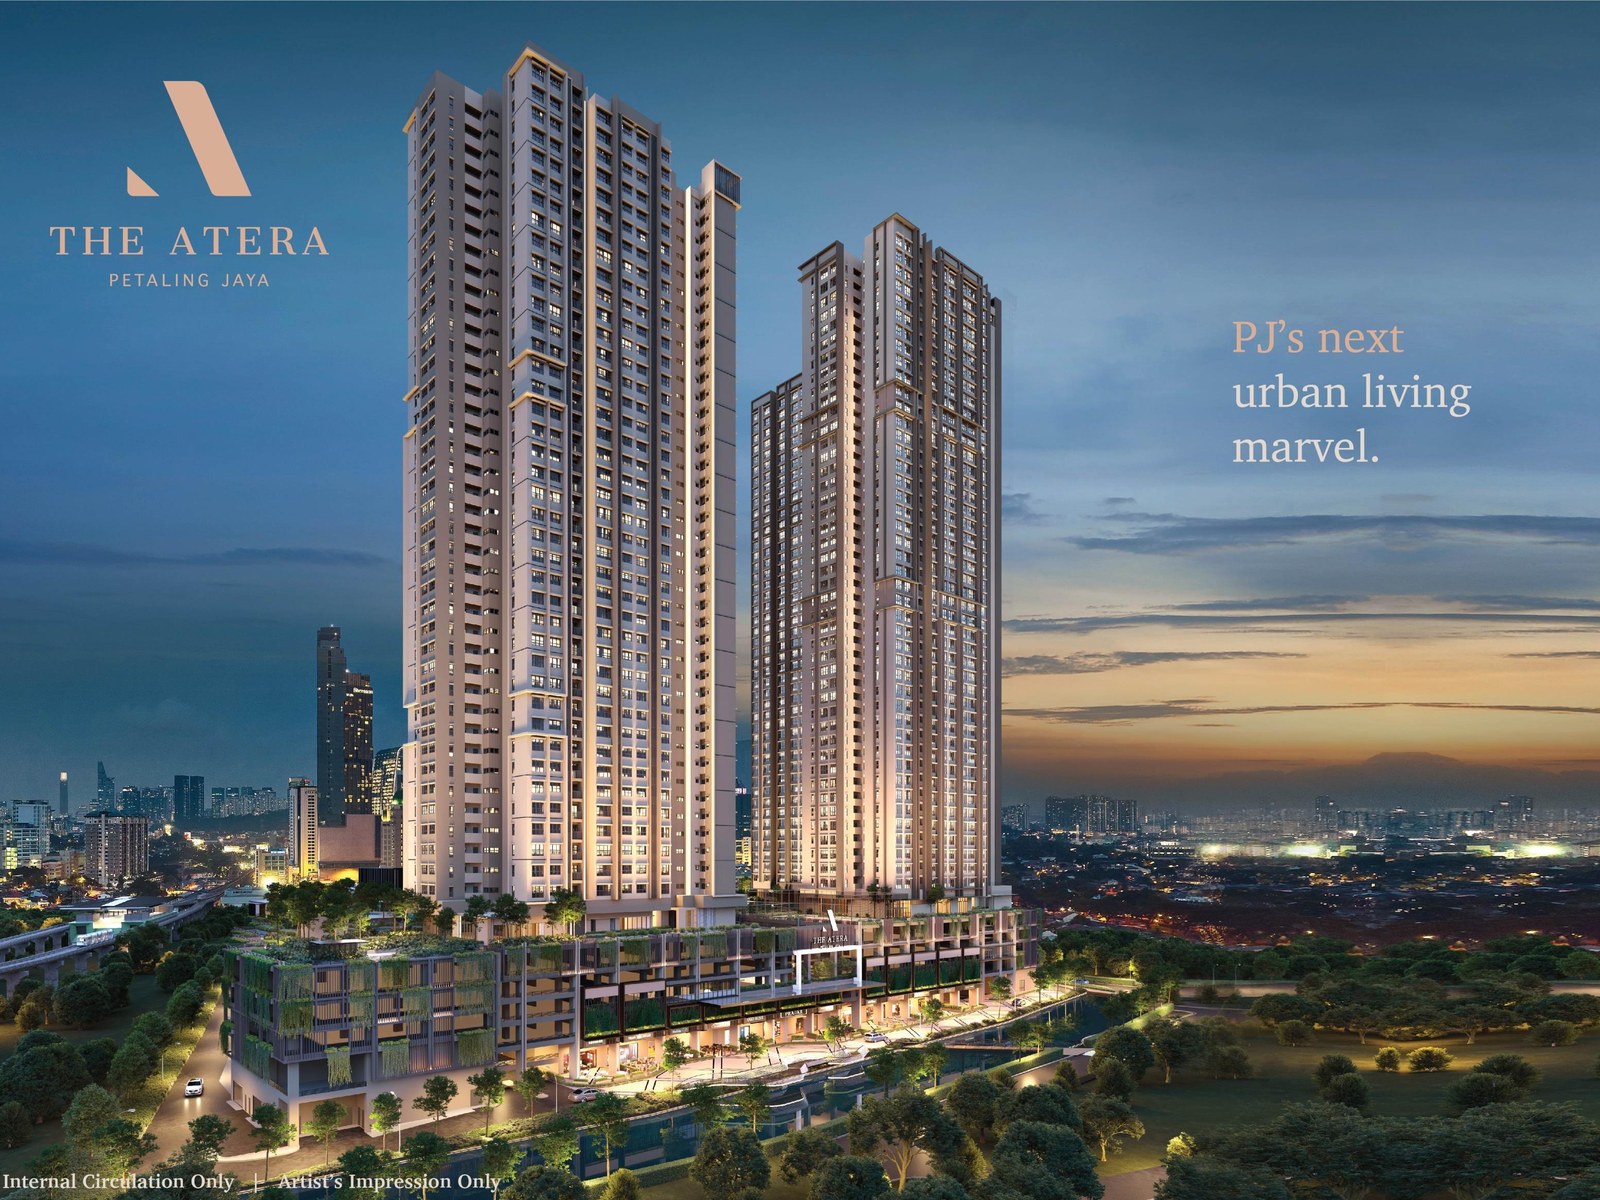
D'Evia's marketed RM498,100 entry, Atera's RM691,000 entry, OAKA's indicative RM836,000 entry and Bangsar Hill Park's RM914,000 entry are reference points, not selected-unit quotes at exactly RM600k, RM800k or RM1m. Use the named type's written price in the calculator. A higher financing margin reduces purchase equity but increases the amount borrowed.
Which budget should I choose?
- Choose the lower price band if the home meets your needs and preserves a useful reserve.
- Choose a higher band only when the extra space or location solves a real need and remains comfortable after recurring costs.
- Test a shorter tenure and higher rate before treating the maximum supported purchase price as your target.
- Check bank eligibility separately; the calculation does not assess income, existing debts or approval.