Which projects are worth checking against the bands?
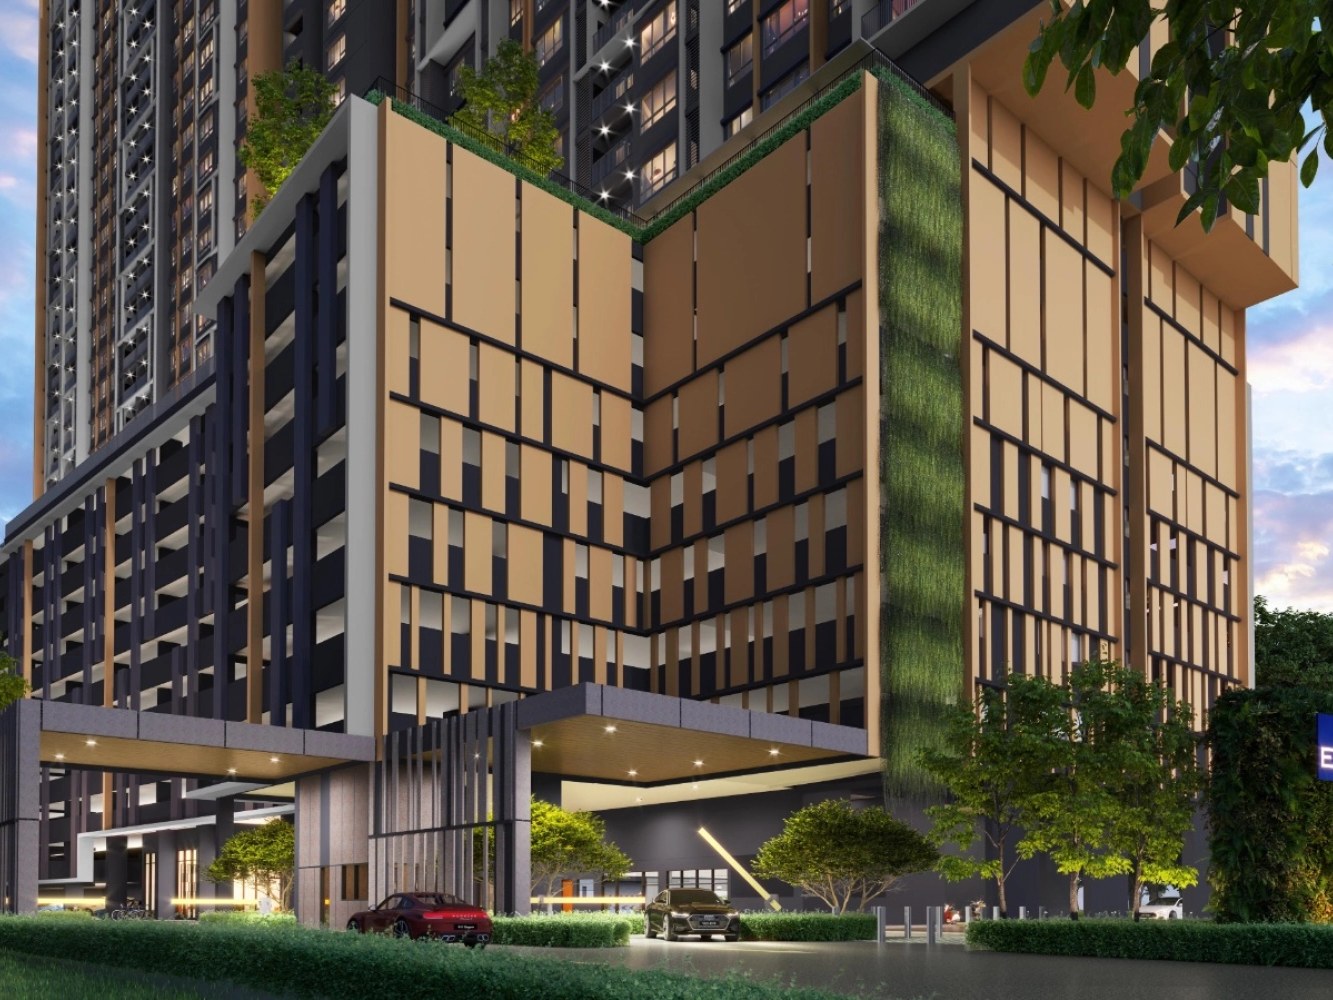
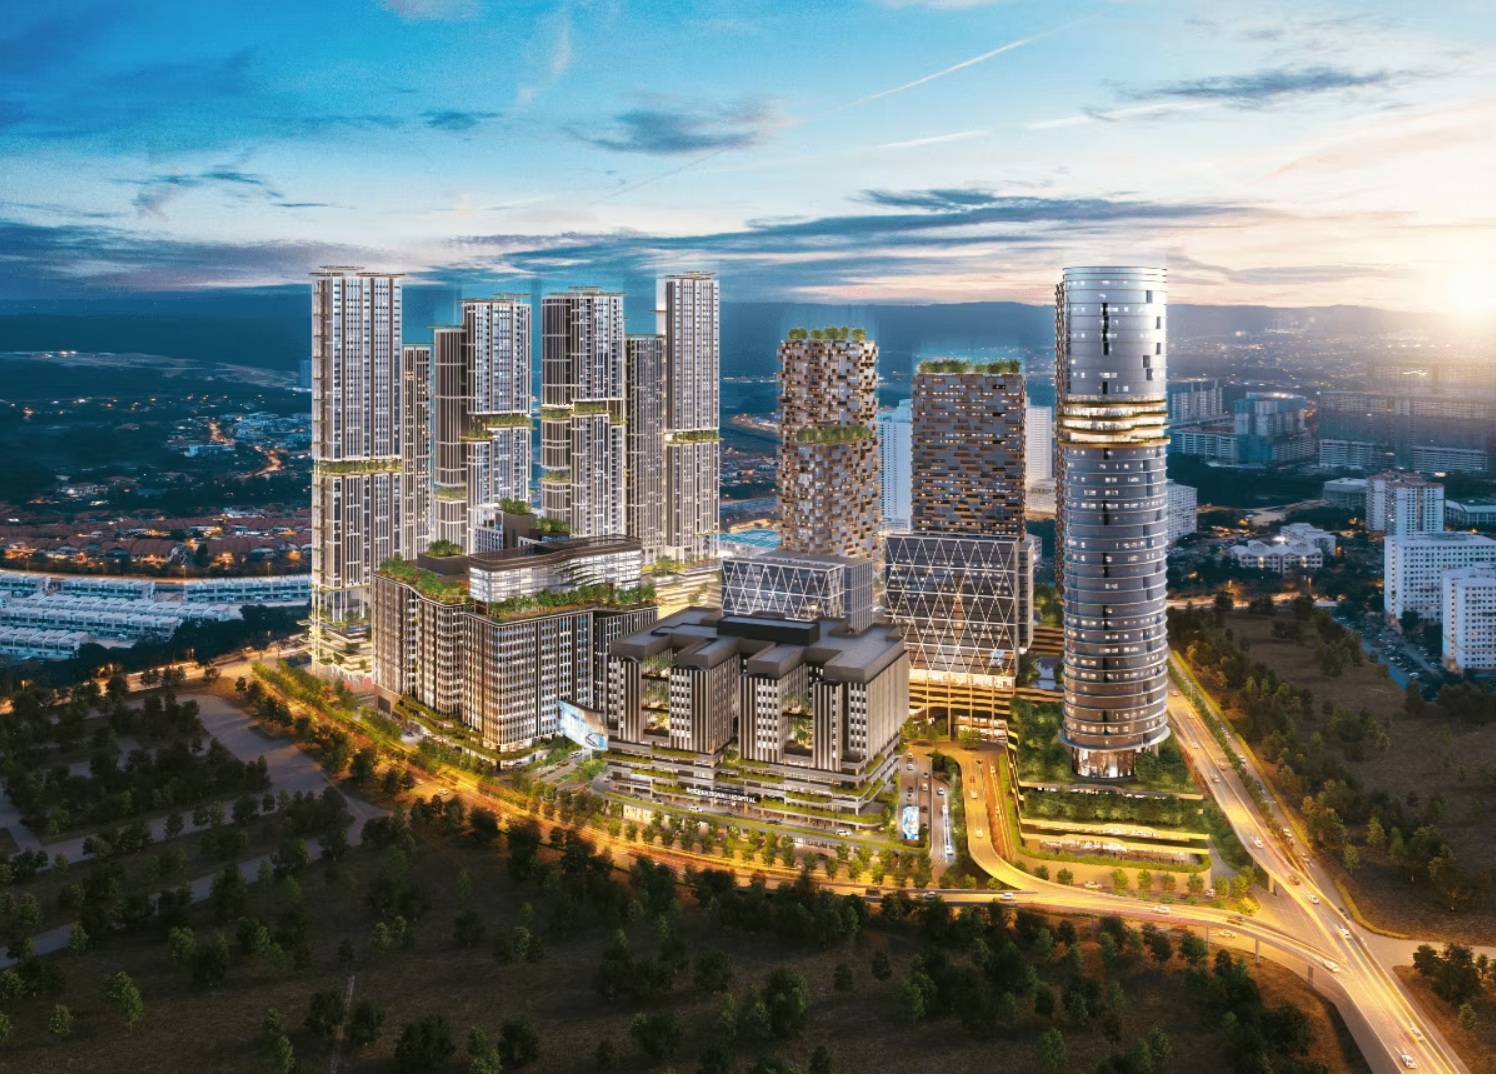
D'Evia's RM498,100 marketed entry and Vividz's RM446,400 indicative entry sit below the calculated RM2,000 mortgage ceiling at these assumptions. Atera's RM691,000 marketed entry sits between the RM2,500 and RM3,000 ceilings. These are project-entry research examples, not confirmed units or three-bedroom quotations. Recalculate with a dated quotation for your selected type.
What if RM3,000 is my total housing limit?
If you reserve RM500 for non-mortgage costs, RM2,500 remains for repayment. That RM500 is a planning allowance, not a verified maintenance bill. Replace it with your actual charges, and leave room for repairs, commuting and a rate increase. A shorter eligible loan tenure reduces the supported loan at the same monthly payment.
How these limits are calculated
We invert the same reducing-balance formula used by the site's loan calculator: loan = monthly repayment x [1 - (1 + monthly rate)^(-number of months)] / monthly rate. Divide the loan by 0.90 to obtain the purchase price under the assumed 90% financing margin.
The three rows are hypothetical mortgage budgets, not available properties or total housing budgets. Each uses 420 monthly payments and 4% annual interest. Figures are rounded; approved financing, product structure and actual rates can differ.
What belongs in the non-mortgage allowance?
List maintenance and sinking fund, insurance, assessment and other applicable ownership charges, repair provision and any paid parking. Decide explicitly whether your RM3,000 also includes household utilities. Annual bills should be divided by 12 for planning, while retaining enough cash when the bill falls due.
The table excludes your other debts, general living expenses, transport, upfront fees, renovation and emergency reserve. It is not a household affordability assessment. A higher maintenance bill reduces the amount left for financing; it does not disappear because a brochure quotes only the loan instalment.
Compare areas only after the home qualifies
Keep the same minimum bedrooms, usable plan and monthly-cost method when comparing PJ, Subang, Puchong or Bukit Jalil. Do not compare a compact one-bedroom starting price with a family three-bedroom quotation. If no qualifying unit quotation exists, the area remains a research option, not a recommendation within budget.
A cheaper home farther from work may release cash for transport but consume more time. Record both the extra monthly travel cost and additional journeys. A smaller home close to work is a trade-off only if it still accommodates the household.
The deposit is a separate cash test
At the RM627,357 illustration, a 10% purchase-price contribution is about RM62,736. This is not the total upfront cash required. Obtain separate quotations for financing and purchase costs, insurance, furnishing and any applicable taxes or fees. Do not assume an advertised package covers everything.
Re-run the calculator with a higher rate, a shorter tenure and lower financing. Keep the home below the tightest comfortable limit rather than using the largest theoretical loan.