Two starting-price examples, using the same loan assumptions
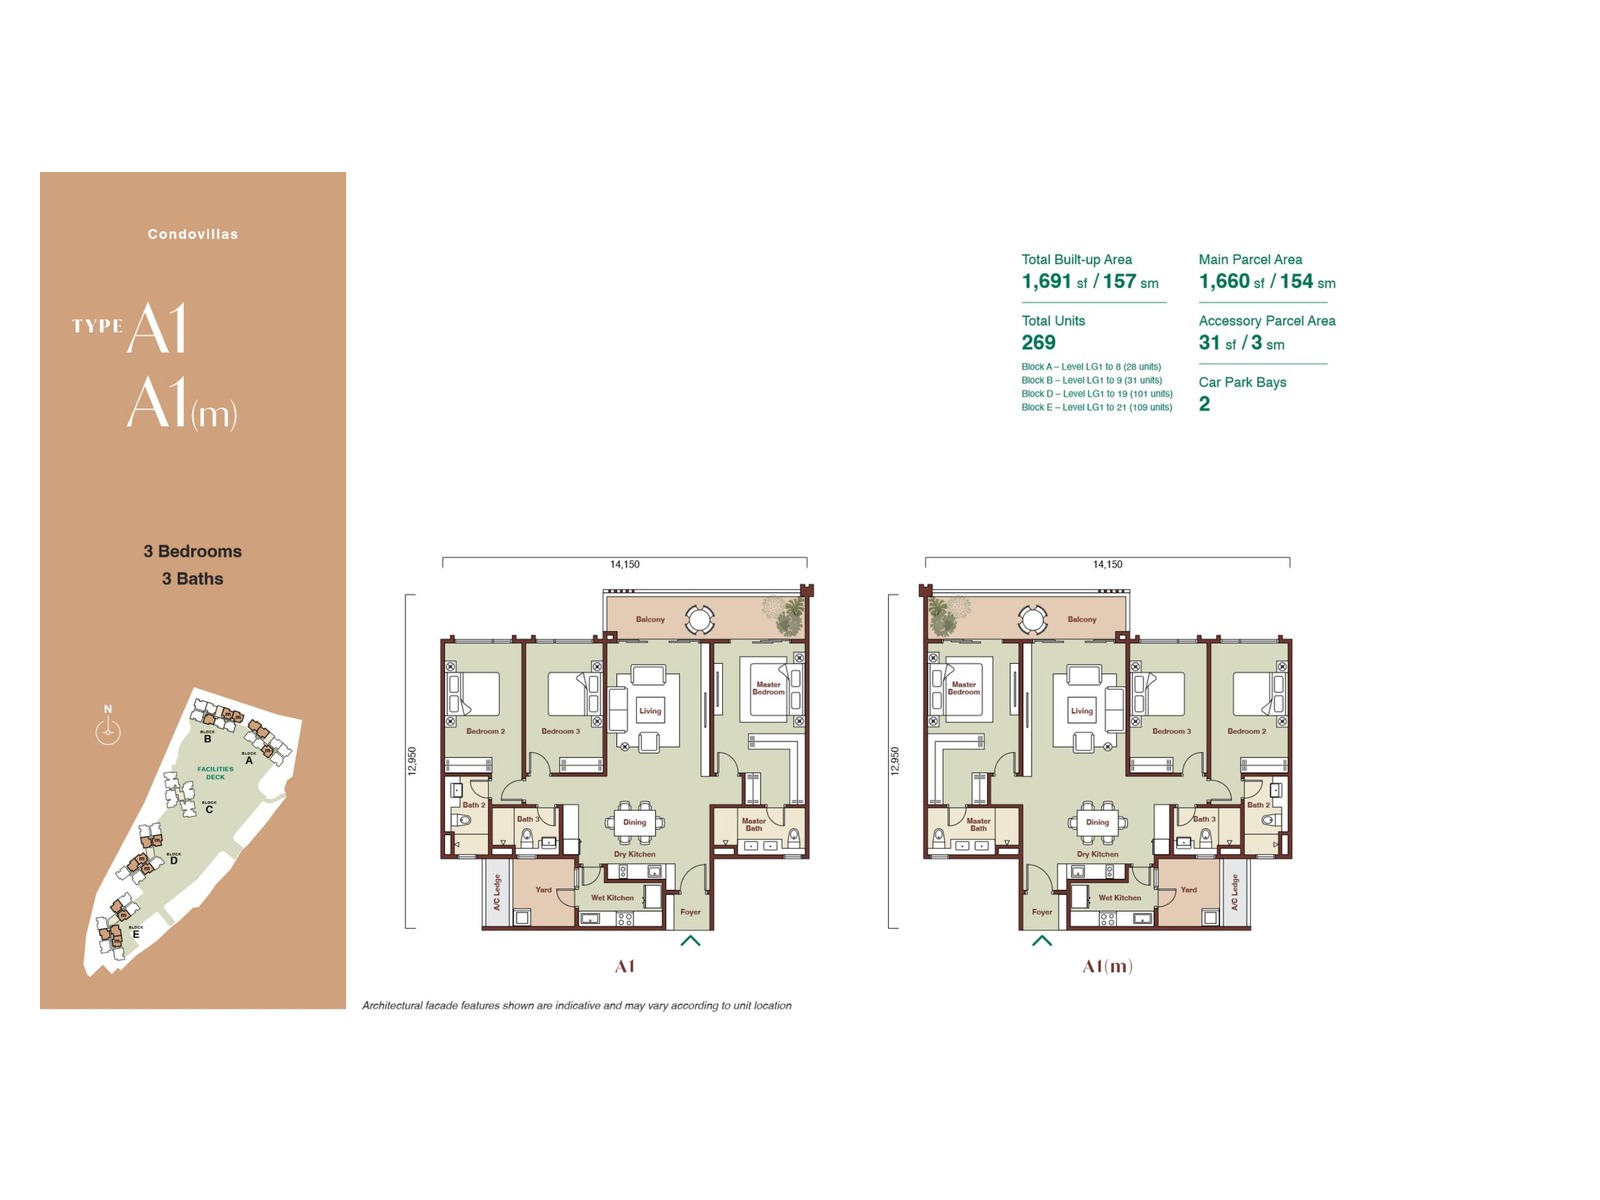
For a RM1.25 million CondoVilla, 90% financing produces a RM1.125 million loan. At 4.0% per year over 35 years, the estimated instalment is approximately RM4,981 per month. The initial 10% buyer equity is RM125,000 before other purchase and setup costs.
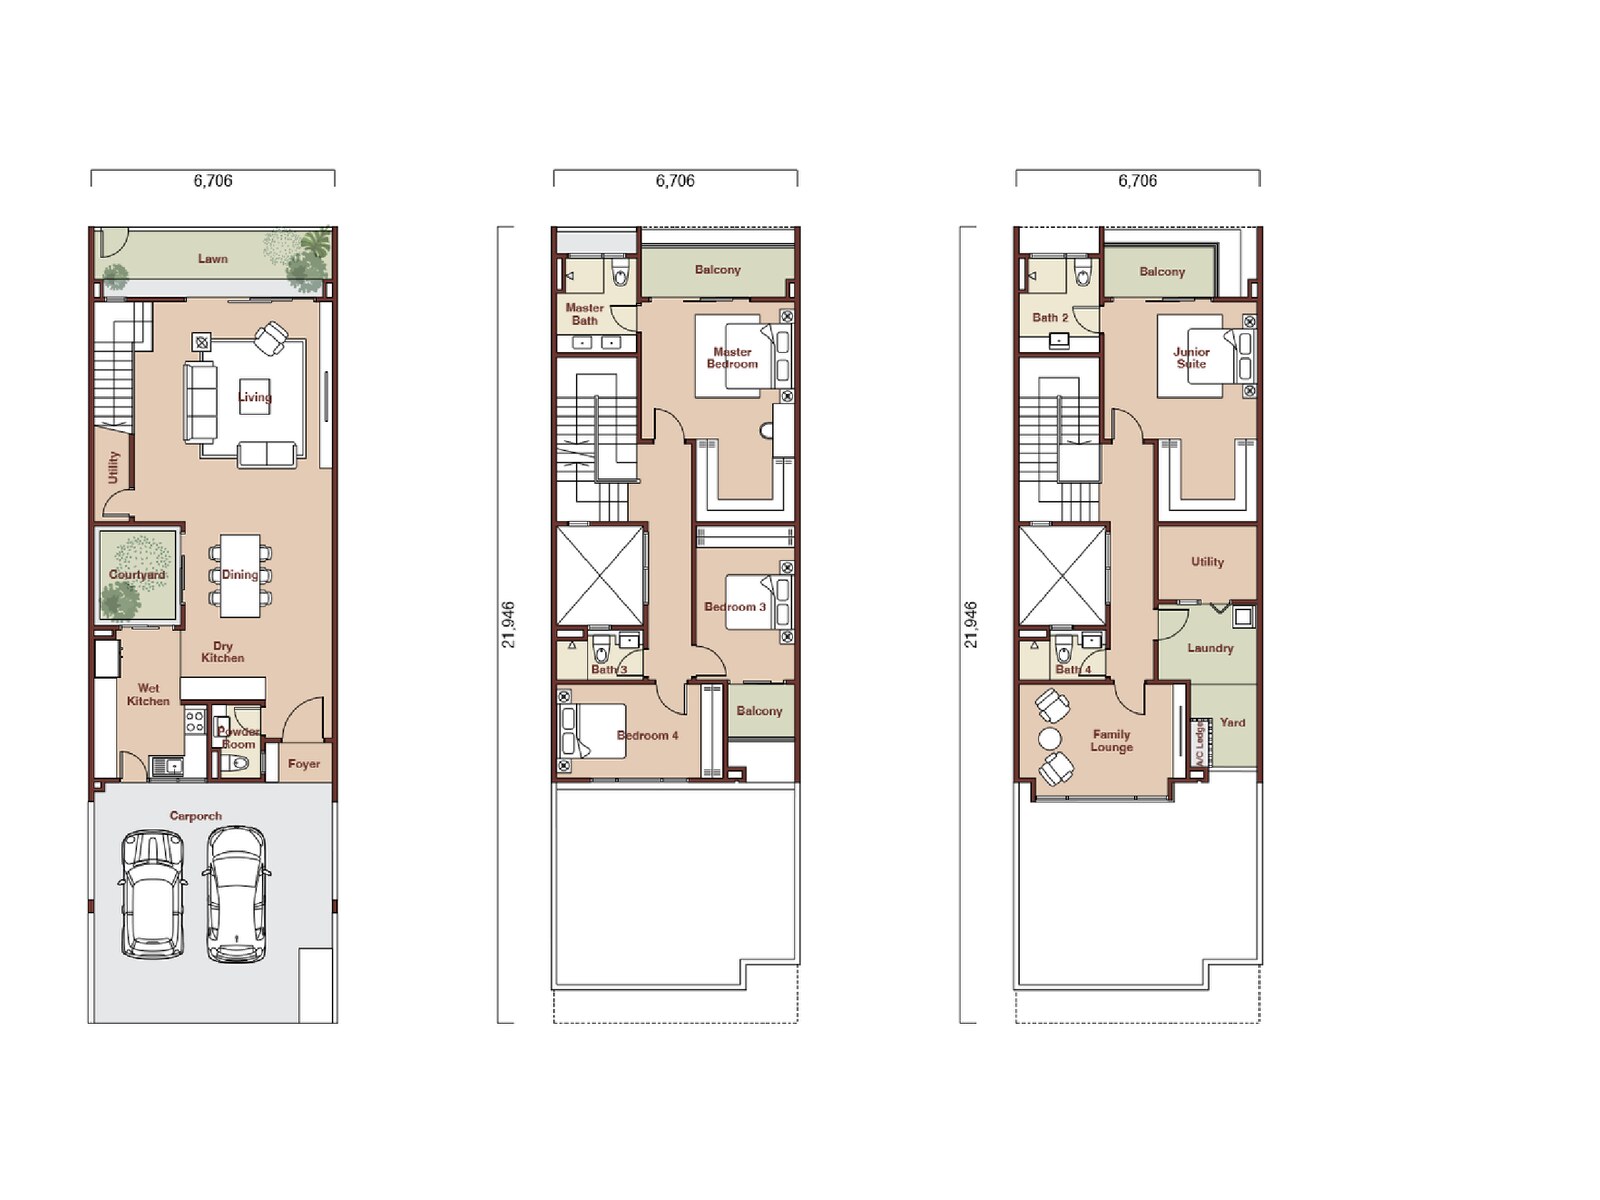
For a RM2.4 million Parkhome, 90% financing produces a RM2.16 million loan. Under the same rate and tenure, the estimated instalment is approximately RM9,564 per month. The initial 10% buyer equity is RM240,000 before other costs.
These are comparison examples, not quotations. A different interest rate, tenure or approved loan margin changes both the cash requirement and monthly payment.
Assumed loan margin
90% of purchase price. Some buyers or properties may receive a different margin.
Assumed interest rate
4.0% per year. Test higher rates as a buffer rather than relying on one number.
Assumed tenure
35 years. Eligibility depends on age and bank policy.
Not included
Duties, legal and valuation costs, insurance, renovation, furnishing, maintenance and recurring ownership expenses.
The 10% equity is not the complete cash requirement
There is no rebate according to Jack’s 9 October 2026 update. Prepare the 10% downpayment plus loan legal fees, then confirm other applicable transaction, financing and setup costs for the selected home. If the approved loan margin is lower than 90%, the cash contribution rises.
If paying the initial costs would leave too little reserve, compare Accent, RIA, Linari and Daya using their current written packages. Do not assume any alternative automatically includes legal fees.
Do not use every available ringgit for the initial purchase. Keep an emergency and renovation buffer after paying the confirmed cash costs.
A bank approval is not the same as a comfortable purchase
Banks assess income, existing commitments, credit records, age and other factors. Even when a loan is approved, the household should test whether the instalment remains comfortable together with maintenance, utilities, insurance, transport, education and normal living expenses.
For a pioneer-phase township purchase, holding power matters because surrounding construction and future amenities may take time. The decision should still work without immediate rental income or quick appreciation.
Stress-test the rate
Run the calculator above your expected interest rate and compare the difference.
Protect cash flow
Allow for periods of vacancy, repairs, family changes and higher living costs.
Compare products
A CondoVilla may preserve more monthly flexibility than a Parkhome even when both offer attractive space value.
Use net income
Build your personal budget from take-home income and real recurring commitments.
Calculate the exact available unit, not the brochure headline
Request the current unit chart first. Then enter the actual purchase price, expected loan margin, rate and tenure into the home-loan calculator. Compare the result with your existing commitments and the renovation cash you want to retain.
Only after that should you compare floor, orientation, view and package. A cheaper unit is not automatically better if its position or layout does not suit the household, but the preferred unit should not create financial stress.